
How to Talk to Your Kids About Money (At Every Age)
Money is one of those subjects adults often assume children will understand eventually. We teach them how to cross the street, clean up after themselves, and say please and thank you, but money can remain strangely mysterious. Children see adults tapping cards, ordering things online, withdrawing cash, and occasionally saying, “That’s too expensive,” without necessarily understanding what any of it means.
By Paul Harris on August 19, 2026
Money is one of those subjects adults often assume children will understand eventually. We teach them how to cross the street, clean up after themselves, and say please and thank you, but money can remain strangely mysterious. Children see adults tapping cards, ordering things online, withdrawing cash, and occasionally saying, “That’s too expensive,” without necessarily understanding what any of it means.
The problem is that children are learning about money whether you deliberately teach them or not. They notice how you talk about spending, whether money causes arguments, what you consider worth buying, and how your family responds when someone wants something.
Talking about money does not require turning childhood into a finance course. It means gradually giving children the knowledge and habits they need to make thoughtful financial decisions later.
Ages 3 to 5: Start with the idea that things cost money
Preschoolers do not need to understand budgets, interest rates, or bank accounts. At this age, the goal is simply helping them understand that money is exchanged for things and that resources are limited.
Everyday situations provide plenty of opportunities. At the supermarket, explain that you are choosing what to buy. When they want a toy, you can explain that buying one thing means spending money that cannot also be spent somewhere else.
Physical money can be especially useful because cards and phones make spending almost invisible. Let children hand cash to a cashier occasionally or put coins into a savings jar.
This is also a good age to introduce waiting. If your child wants something small, you do not always have to buy it immediately. Waiting until another day begins teaching the difference between wanting something and needing to have it right now.
Ages 6 to 8: Introduce saving and choices
Once children understand basic numbers, money becomes much easier to explain.
An allowance can be useful at this stage, although families approach allowances differently. Some connect money to chores, while others give a small regular amount specifically to teach financial skills.
Whichever system you choose, give children opportunities to make decisions with their own money.
If they spend everything immediately, resist the temptation to replace it. The small disappointment of realizing they cannot afford something later is a valuable lesson when the stakes are low.
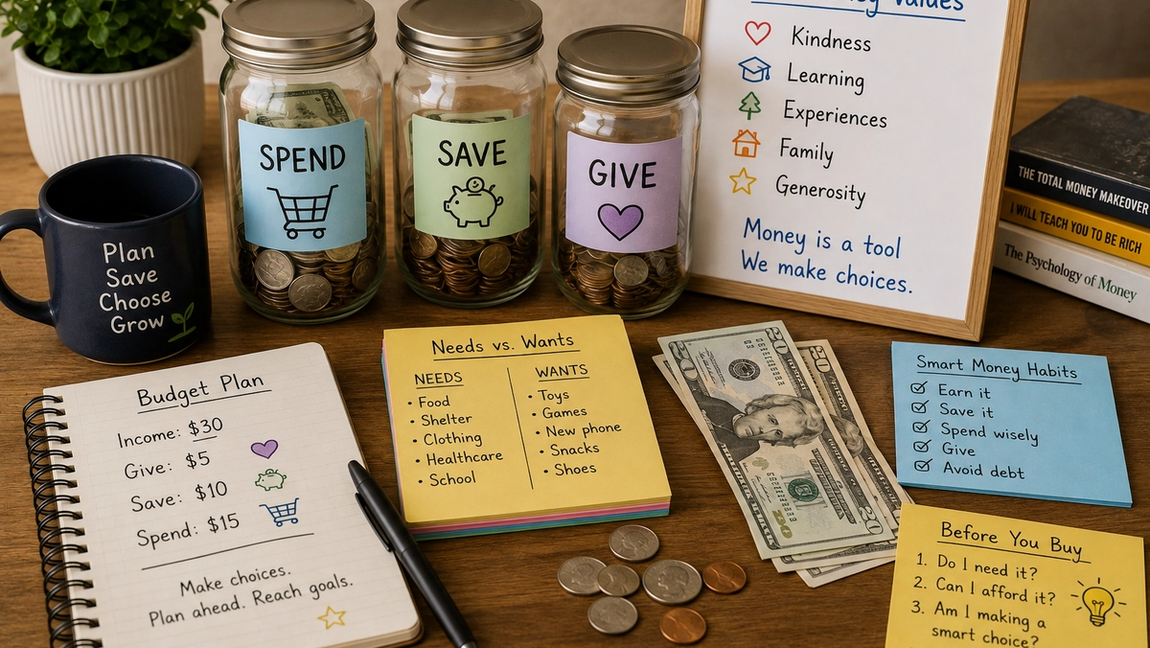
You can also introduce different purposes for money. Some families use separate jars or accounts for spending, saving, and giving. The exact categories matter less than helping children understand that money does not have to be spent immediately.
Ages 9 to 12: Show them how a real household works
Older children can begin understanding where family money actually goes.
You do not need to reveal every detail of your finances, but you can explain that households have regular expenses such as housing, electricity, groceries, transportation, insurance, and internet.
This can be particularly useful because children often see income without seeing expenses. They may hear that someone earns a certain amount and imagine that all of it is available for spending.
Let them participate in small financial decisions. Give them a budget for choosing a birthday gift. Compare prices at the supermarket. Show them how you decide whether a more expensive product is worth buying.
You can also introduce the idea of advertising. Explain that companies deliberately design advertisements, packaging, influencers, and promotions to make people want things.
Learning to recognize persuasion is an important financial skill.
Ages 13 to 15: Teach budgeting and digital money
Teenagers increasingly interact with money digitally, which makes spending feel less tangible.
This is a good time to introduce a simple budget. If your teenager receives an allowance, earns occasional money, or gets money for birthdays, help them decide how much they want to spend and save.
Explain how debit cards and bank accounts work. Show them the difference between the amount in an account and the amount they might want to spend.
Online shopping also creates opportunities to discuss impulse purchases. Encourage them to wait before buying something they suddenly want. Even a 24-hour pause can help separate genuine interest from temporary excitement.
Teenagers should also begin learning about online scams, subscriptions, in-app purchases, and the risks of sharing financial information.
Money education now includes digital safety.
Ages 16 to 18: Explain the financial system they are about to enter
By the late teenage years, financial education should become much more practical.
Explain taxes, paychecks, bank accounts, interest, credit cards, loans, insurance, and basic investing. A teenager entering adulthood should understand that a credit card is borrowed money rather than additional income.
If they have a part-time job, review a paycheck together. Explain why gross pay and take-home pay are different.
This is also a good time to discuss larger financial decisions. Talk about university costs, student loans where relevant, transportation, rent, and what living independently actually costs.
If possible, let teenagers manage increasingly larger budgets themselves. Mistakes involving €50 at 17 are usually much easier to recover from than mistakes involving thousands at 25.
Talk about your values, not just the numbers
Financial education is not only about teaching children how to accumulate money.
Talk about what money is for.
Your family might prioritize travel, education, financial security, generosity, experiences, or having enough flexibility to spend more time together. Other families will make different choices.
Children should understand that spending reflects priorities. Two families earning similar amounts can live completely differently because they value different things.
You can also explain why you sometimes choose not to buy something even when you technically can afford it. Being able to purchase something does not automatically make it worth purchasing.
That distinction becomes increasingly important in a culture built around constant consumption.
Do not make children responsible for adult financial stress
There is a difference between teaching children that money is limited and making them anxious about the family’s finances.
Children do not need to carry adult worries about mortgages, debt, job insecurity, or bills they cannot control.
If money is tight, you can explain decisions honestly without making children feel responsible. “We’re spending less on restaurants right now because we’re saving for other things” gives useful context. Constantly saying, “We can’t afford anything,” can create unnecessary fear.
The goal is financial awareness, not financial anxiety.
Let them see you make financial decisions
Children learn as much from watching as they do from formal conversations.
Let them see you compare prices, save for something, decide against an impulse purchase, donate money, or admit that you bought something you did not really need.
You do not have to pretend you have always made perfect financial decisions either. Age-appropriate stories about your own mistakes can be surprisingly valuable.
Perhaps you spent too much when you first started earning money or waited too long to begin saving. Explain what you learned.
Money becomes less intimidating when children understand that financial skills are learned rather than something adults magically know.
Keep the conversation going
There is no single “money talk” that prepares a child for adulthood.
Financial education happens through hundreds of small conversations. It happens at the supermarket, when a child wants a new toy, when a teenager receives their first paycheck, and when the family discusses where to go on vacation.
The details should become more sophisticated as children grow, but the underlying message can remain remarkably consistent: money is a tool. It requires choices. Those choices have consequences.
If children grow up comfortable asking questions about money, they enter adulthood with an enormous advantage.
They may not make every financial decision perfectly. None of us do. But they will understand what they are deciding—and that is a much better place to start.


